Card Payments for Rent, Maintenance Fees, and Labor Costs: A Practical Guide
Managing monthly fixed expenses is one of the most persistent challenges for both households and small business owners in Korea. Whether it is monthly rent, building maintenance fees, or staff wages, these recurring costs can put serious pressure on cash flow. Fortunately, card-based payment services now make it possible to handle all three categories with a credit or debit card, giving payers more flexibility and breathing room. This article breaks down how each service works, who benefits most, and what to look for when choosing a provider.
Why Fixed Monthly Expenses Are Hard to Manage
Most recurring obligations — rent, maintenance charges, and labor costs — have traditionally been settled by bank transfer. That means cash must be available on a specific date every month, with no flexibility. For a small shop owner waiting on receivables, or a tenant who just moved and faces overlapping deposits, the timing can be brutal. Card payment services step in by allowing the payer to use available credit, effectively shifting the actual cash outflow to the card’s billing cycle. This gap, sometimes 30 to 45 days, can make a meaningful difference in day-to-day financial management.
Monthly Rent Paid by Card
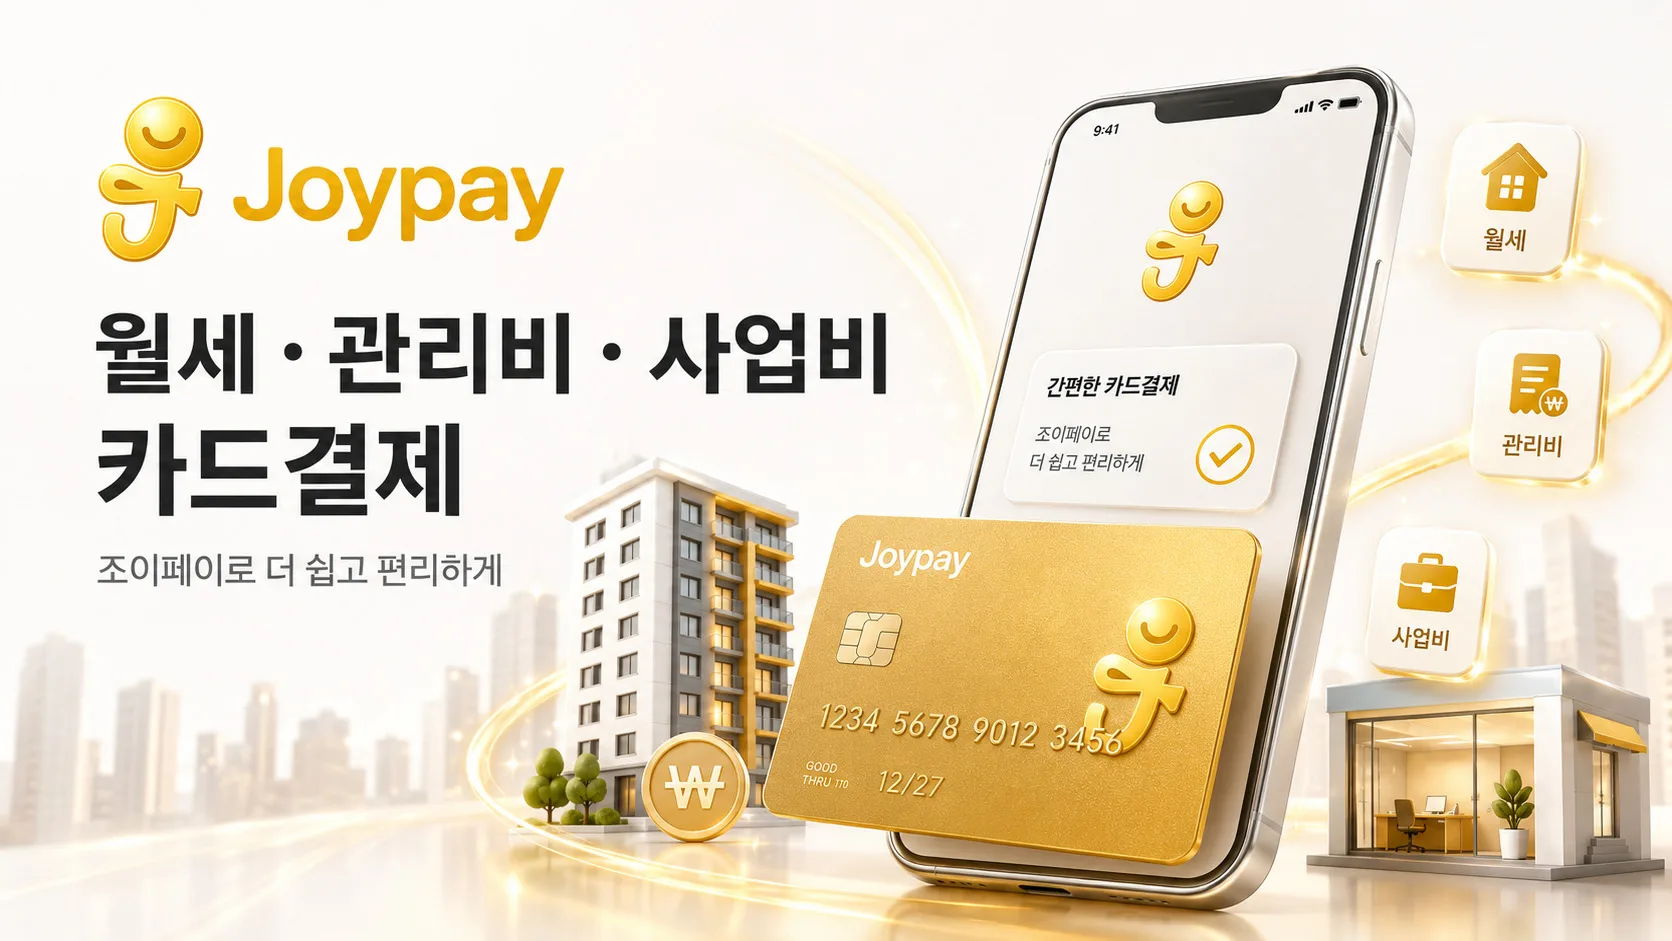
Rent card payment services let tenants pay their monthly rent — traditionally settled by direct bank transfer — using a credit or debit card instead. The service provider collects the card payment from the tenant and forwards the equivalent cash to the landlord, who receives it just as they would from a standard transfer. The landlord’s experience is unchanged, while the tenant gains the benefit of their card’s billing cycle and any rewards points that may apply. This is especially useful for tenants in studio apartments, officetels, or small commercial spaces where monthly rent is a significant fixed cost.
Maintenance Fee Payments by Card
Apartment and officetel residents receive a monthly maintenance bill covering shared building services such as cleaning, security, elevator operation, and common-area utilities. Paying this by card is now straightforward through dedicated platforms. The amount is charged to the card, and the building management office receives the funds on schedule. Some platforms support both credit and debit cards, making this option accessible even to those who prefer not to carry revolving debt. Regular card use here can also help users accumulate points on an expense that would otherwise earn nothing.
Labor Cost Payments by Card
For business operators, wage and service-fee obligations are often the largest monthly outflow. Using 인건비카드결제, employers can pay staff salaries, part-time wages, and outsourced service fees via credit card rather than immediate bank transfer. The payment agency processes the card charge and disburses the funds to the recipients, while the business owner’s actual cash payment is deferred to the card’s settlement date. This approach is particularly valuable for small businesses experiencing a temporary gap between income and outgoing obligations, helping them avoid short-term borrowing or late payments.
Key Benefits at a Glance
- Cash flow flexibility: credit card billing cycles provide a natural buffer between obligation and actual cash outflow.
- Rewards accumulation: points, miles, or cashback on expenses that previously earned nothing.
- Simplified record-keeping: card statements provide a clean, itemized history of all payments made.
- No disruption for recipients: landlords, building managers, and staff all receive funds through normal channels.
Comparing the Three Payment Categories
| Payment Type | Who Benefits | Typical Card Types Accepted | Main Advantage |
|---|---|---|---|
| Monthly Rent | Tenants in residential or commercial spaces | Credit, Debit | Deferred cash outflow, rewards points |
| Maintenance Fees | Apartment and officetel residents | Credit, Debit | Convenience, points on routine bills |
| Labor Costs | Small business owners, sole traders | Credit | Cash flow relief, avoids short-term loans |
What to Check Before Signing Up
Service Fees
Most card payment intermediaries charge a processing fee, typically a percentage of the transaction amount. This fee varies by provider and payment category, so it is worth comparing a few platforms before committing. In many cases, the rewards earned on the card transaction offset a portion of the fee, making the net cost lower than it first appears.
Processing Time
Confirm how quickly the recipient receives funds after the card is charged. Reputable services typically transfer funds within one to three business days, ensuring landlords and employees are paid on time even though the payer’s cash has not yet left their bank account.
Supported Cards and Limits
Not every platform supports all card issuers or all card types. Check that your preferred card is accepted and that the monthly transaction limit is sufficient for your needs, especially if you are handling larger payroll amounts.
Making the Most of Card Payment Services
Card-based payment services for rent, maintenance, and labor costs are not just a workaround for cash shortages — they are a practical financial tool that can be used proactively. By timing card payments strategically within the billing cycle, users can consistently hold onto cash a little longer each month, giving themselves a reliable cushion. Combined with rewards programs, the cumulative benefit over a year can be surprisingly substantial. The key is to treat the card balance as a planned obligation rather than additional debt, ensuring it is cleared on schedule to avoid interest charges that would cancel out any gains.